Debt Payoff Planner Bundle
Become debt free with one complete printable system.
$3.75 $14.99
Buy on Etsy →
Debt Payoff
Pay off debt faster with a written plan, not a wish.
Most debt payoff advice stops at pick a method and try harder. This planner is the part after that. It is a 20 page printable system that takes you from a messy pile of statements to one written payoff order you can follow month after month. You list every debt, you rank them, and then you track every payment until the balances hit zero.
Nothing here is complicated on purpose. The pages are built to be filled in with a pen in a few sittings, then used for a few minutes each month. If you have ever made a plan in January and lost it by March, the monthly trackers are the fix. They keep the plan visible and the progress undeniable.
The debt snowball pays your smallest balance first. You get a win fast, and that win keeps you going. The debt avalanche pays your highest interest rate first. You pay less interest overall, which is the mathematically cheapest route. Most people have a strong opinion about which one fits them, and most people have never actually run the numbers on their own debts.
The ranking worksheets in this planner do exactly that. You enter each debt once with its balance and interest rate, then the worksheets lay out your payoff order under each method side by side. You can see the tradeoff in plain numbers and pick the order you will actually stick with. There is no wrong answer here. The best method is the one you follow.
Twelve monthly payoff trackers carry you through a full year of payments. Each month you record what you paid, what is left, and how the balances moved. Over the year those pages become a record of real progress, which matters on the months when it feels like nothing is changing. The milestone pages give you places to mark the big moments, like the first debt fully paid off.
The interest saved calculator is the page that changes how extra payments feel. It shows what an additional payment each month actually saves you over the life of the debt. The worked example walks through an extra 200 dollars a month on 5,000 dollars of credit card debt and shows how many thousands that saves in interest. Once you see that number for your own debts, the extra payment stops feeling optional.
This planner fits anyone carrying more than one debt and feeling the weight of keeping it all in their head. Credit card balances, a car loan, a personal loan, medical bills, student loans. If you have two or more payments going out and no single place where the whole picture lives, this is for you.
It also fits people who have tried apps and quit them. An app hides your plan behind a login screen. A printed planner sits on your desk or your fridge and stares back at you. If writing things down by hand is what makes a plan feel real to you, this format was built for you.
Apps are good at math and bad at motivation. They send a notification you swipe away. A printed tracker you filled in yourself is harder to ignore, because your own handwriting is on it. Every payment you log is a small ceremony that says the plan is working.
A printable also costs you nothing after the download. No subscription, no account, no data harvesting, no feature locked behind a paywall. Print the pages you need, reprint the monthly trackers as the year goes on, and keep the whole system in a binder or on a clipboard. When the last debt is paid, you will have a physical record of exactly how you did it.
Download the PDF and print the pages you need. Start with the debt inventory and the ranking worksheets.
List every debt, then use the worksheets to rank them by the snowball or the avalanche method and pick your payoff order.
Each month, log your payments in the monthly tracker, update your balances, and mark your milestones as debts fall.
What buyers ask before downloading this planner.
The planner includes worksheets for both, so you do not have to decide before you start. The snowball pays smallest balances first for quick wins that keep you motivated. The avalanche pays highest interest rates first and costs less in total interest. Rank your debts both ways, look at the numbers, and choose the order you will actually follow. Consistency beats optimization.
Yes. The twelve monthly trackers are worked through in order starting with month one, so you begin whenever you are ready. There is no January only design here and no pages go to waste.
Any home printer and standard letter size paper. A binder or folder keeps the pages together, and a pen is all you need to fill them in. Heavier paper holds up better if you plan to handle the pages a lot.
Yes. Import the PDF into any annotation app and write on the pages with a stylus. It works the same way on paper or on screen.
No. This is an organizational tool that helps you track and plan your own payoff strategy. It does not tell you which debts to pay and it does not give investment, tax, or legal advice. For advice about your specific situation, talk to a qualified professional.
The planner still helps. The inventory and the monthly trackers give you a clear payoff timeline and the interest calculator shows what extra payments save you. But it shines brightest with two or more debts, where the ranking worksheets earn their keep.
Planners from the same collection, built to work together.
Become debt free with one complete printable system.
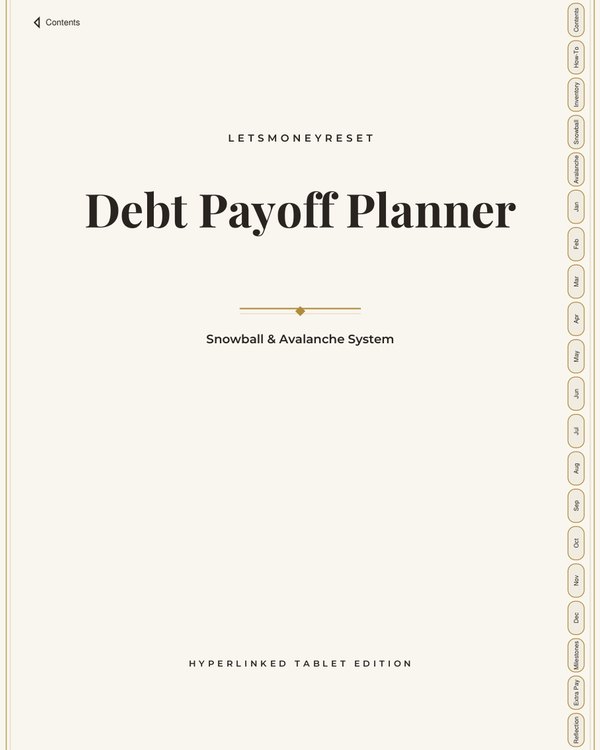
Your debt payoff plan, made for your iPad.
Save $1,378 in 2027, one weekly deposit at a time.
Join the list and get the free monthly budget worksheet plus first word on new planners.
No spam, ever. Unsubscribe anytime.